Indian residents and resident Hindu Undivided Families (HUFs) can apply their unused basic exemption limit to certain capital gains that are taxed at a special rate such as short-term capital gains on specific listed securities and long-term capital gains that fall under special provisions, helping to lower their tax burden.
On the other hand, non-residents, firms and companies can’t claim this adjustment for capital gains taxed at a special rate. However, NRIs can still use the basic exemption limit to reduce their income tax liability on capital gains taxed at normal slab rates.
For example, short term capital gains (STCG) from market linked debentures or MLDs, listed bonds and debentures and gold ETFs are taxed at slab rates for NRIs. So if you have STCG from these sources, you can apply the Rs 4 lakh basic exemption limit under the new tax regime to reduce your tax liability.
For example, if you earned Rs 2 lakh STCG from listed bonds and that’s your total income in India for the year, you can use the Rs 4 lakh basic exemption limit under the new tax regime to wipe out any tax liability from that STCG.
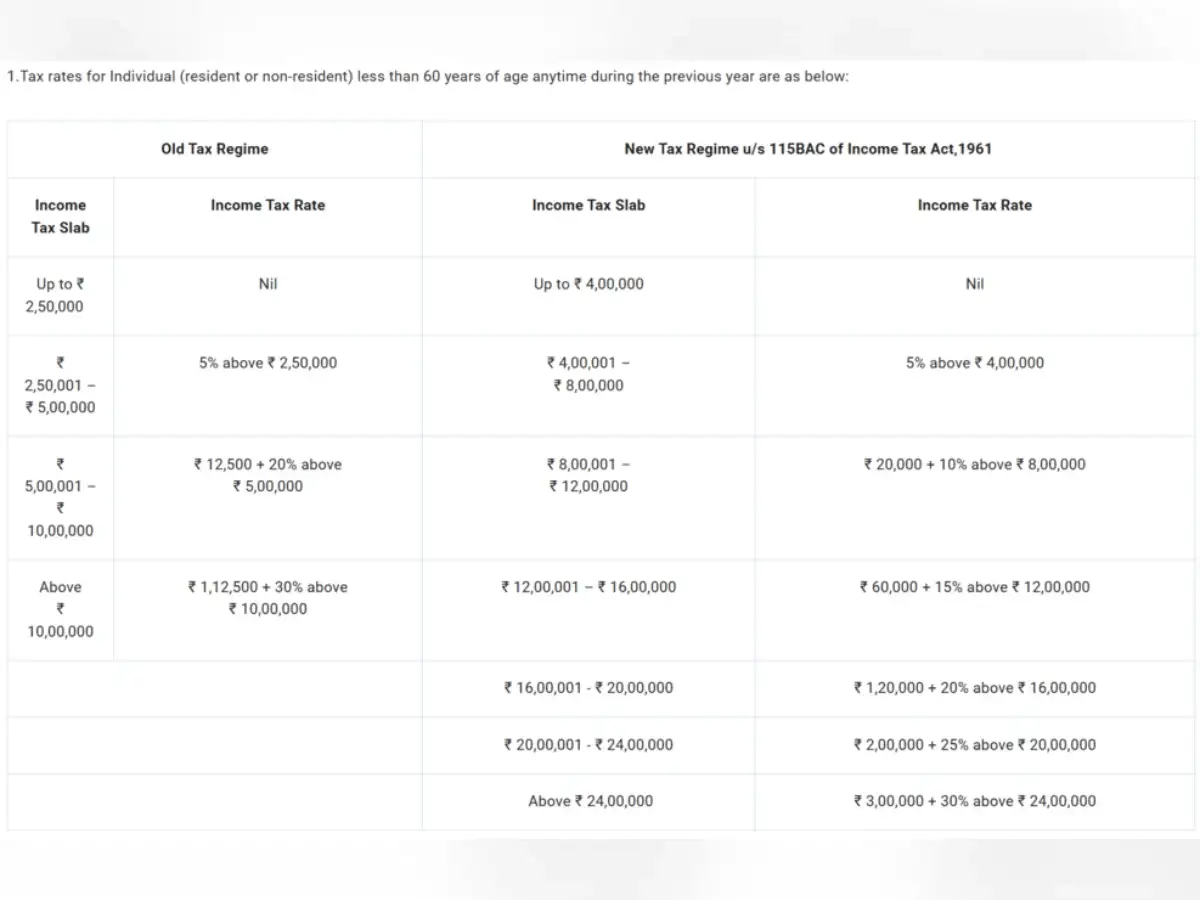
Basic Exemption limit Source: Income Tax Website
Why can’t NRIs use the basic exemption limit to adjust in special rate incomes?
The Income Tax law says that non-residents cannot adjust the unused basic exemption limit against capital gains taxable at special rates under Sections 111A, 112 or 112A.
Surana says: “These income tax legal provisions (111A, 112 or 112A) specifically grant this adjustment only to a resident individual or a resident HUF.”
Therefore, a non-resident must generally pay tax at the applicable special rate on the entire amount of such capital gains.
Surana explains this by using an example. Let’s assume a non-resident earns interest income of Rs 1.5 lakh and short-term capital gains of Rs 4 lakh on listed equity shares covered under Section 111A during FY 2025–26. Although the interest income falls below the basic exemption limit, the non-resident cannot use the unused portion of that limit against the short-term capital gain.
The entire gain of Rs 4 lakh will attract tax at 20%, resulting in tax of Rs 80,000 and a health and education cess of Rs 3,200. The total tax liability will therefore amount to Rs 83,200.
However, this restriction applies only to capital gains that attract a special tax rate.
Surana says: “If a non-resident earns ordinary short-term capital gains taxable at normal slab rates, such gains form part of the income taxable under the regular slabs, and the applicable basic exemption limit may reduce the tax liability.”
A non-resident also cannot claim the rebate under Section 87A. However, it should be noted that a tax treaty like a double tax avoidance agreement (DTAA) may provide a more beneficial treatment in some cases, depending on the NRI’s country of residence, the nature of the asset and the relevant treaty provisions.

